By Samuel Abasiekong-Abasiekong
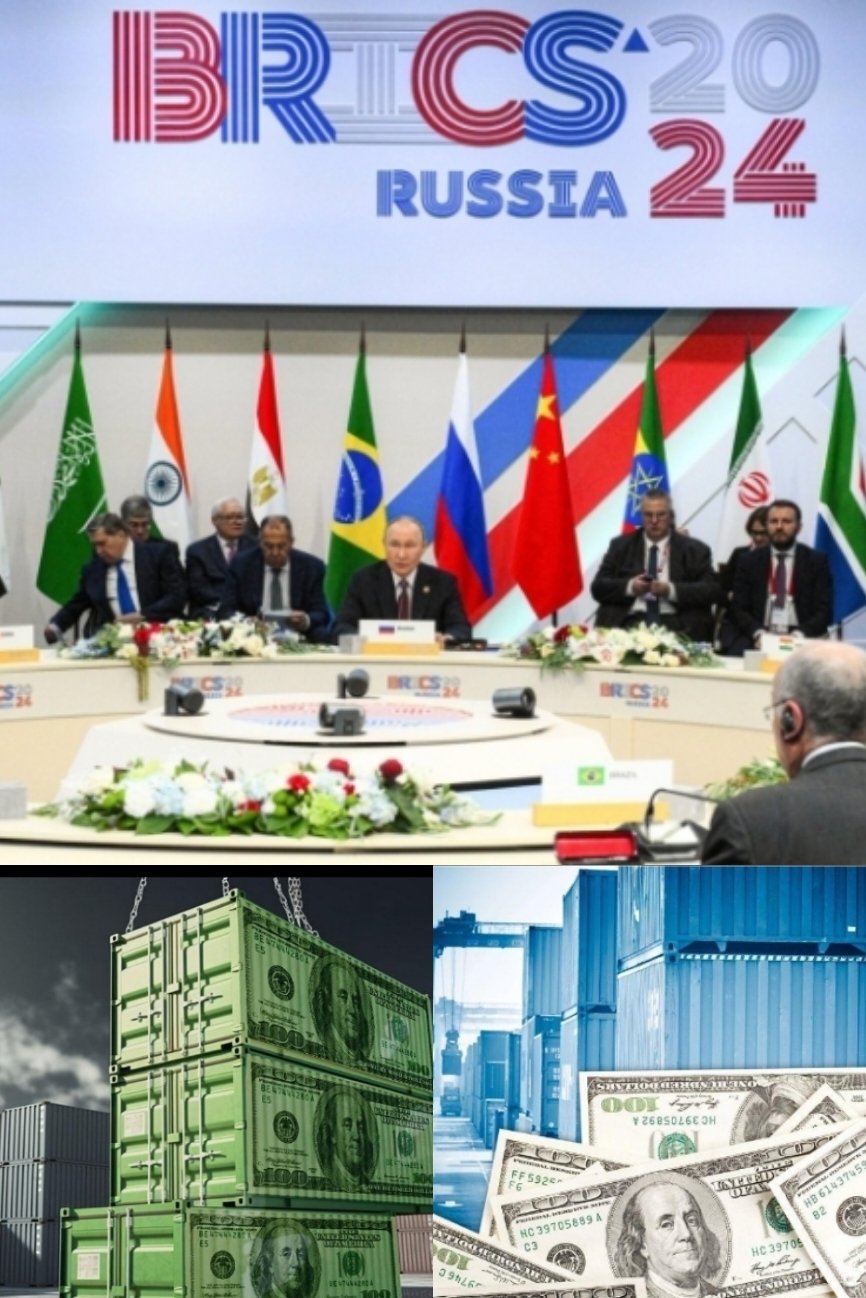
As BRICS expands its economic reach and explores alternatives to Dollar-dependent trade, the world faces a critical question: will the US Dollar lose its global dominance, or will the emerging financial order simply give countries more choices?
The future of the US Dollar is increasingly tied to one of the most consequential economic developments of the 21st century: the attempt by the BRICS group of nations to reduce dependence on Western-dominated financial systems.
BRICS—originally Brazil, Russia, India, China and South Africa—has evolved from a small coalition of emerging economies into a broader platform for cooperation among countries seeking a stronger voice in global economic governance.
Its ambitions extend beyond trade. They include reforming international financial institutions, expanding the use of national currencies, strengthening development finance and exploring payment arrangements that could reduce the need to use the Dollar in transactions between participating countries.
But what would happen if these initiatives reached full maturity? Would the Dollar lose its position as the world’s principal reserve currency, or would it remain dominant while sharing more of its influence with competing currencies?
The answer depends on understanding what BRICS is actually building, what the dollar’s dominance rests upon, and how difficult it would be to replace a financial system that has developed over generations.
1. BRICS AT A TURNING POINT: THE REAL MEANING OF “FULL CIRCLE”
The phrase “BRICS coming full circle” describes a possible future in which the bloc’s economic cooperation develops into a functioning alternative network for international trade, payments, investment and development finance.
It does not necessarily mean the creation of one new currency to replace the dollar. In fact, the distinction is central to understanding the group’s actual strategy.
At the 18th BRICS Summit, held in New Delhi on September 12–13, 2026, leaders continued to emphasise a more representative international order and stronger financial and economic cooperation. India’s government subsequently clarified that there was no proposal for a common BRICS currency at that time. Instead, discussions centred on local-currency settlements and more efficient cross-border payment arrangements.
That position changes the terms of the debate.
BRICS does not have to invent a single currency to reduce the dollar’s influence. If Brazil can pay China in renminbi, India can settle some transactions in rupees, and participating banks can transfer funds through interoperable payment systems without routing every transaction through dollar-based channels, the dollar’s role could diminish in those specific transactions.
If such arrangements spread across energy, agriculture, industrial production, technology and investment, the cumulative effect could become significant.
The question, therefore, is not simply whether BRICS will launch a new currency. It is whether the group can build a sufficiently reliable financial network for countries to conduct a growing share of international business without needing the US Dollar at every stage.
2. THE DOLLAR’S EXTRAORDINARY POWER: WHY AMERICA STILL HOLDS THE ADVANTAGE
For decades, the US Dollar has served as the world’s leading reserve currency, a major medium of international exchange and a benchmark for financial markets.
Its influence extends far beyond the United States. Governments hold dollar reserves to support their currencies and meet external obligations. Commercial banks use Dollars in international lending and settlement. Companies issue Dollar-denominated debt, while global investors buy US Treasury securities as a major reserve and investment asset.
According to the US Federal Reserve’s July 2025 review, the dollar’s international position is supported by the size of the American economy, confidence in its financial institutions, the depth of its capital markets and the availability of substantial dollar-denominated assets.
The scale of this advantage is evident in the latest International Monetary Fund data available for the first quarter of 2026.
GLOBAL OFFICIAL FOREIGN-EXCHANGE RESERVES · Q1 2026
57.13% US Dollar
20.03% Euro
1.99% Chinese Renminbi
Source: IMF COFER, published July 1, 2026. These are shares of allocated official foreign-exchange reserves, not shares of all global financial assets.
The figures reveal the scale of the challenge facing BRICS. Although China is a major trading power, its currency still represents only a small share of allocated global official reserves.
The Dollar’s dominance also extends into foreign-exchange markets. The Bank for International Settlements reported that the Dollar was on one side of approximately 88% of global foreign-exchange transactions in April 2022. Because currencies are traded in pairs, these percentages overlap and should not be added together.
The implication is clear: replacing the Dollar is not merely a matter of announcing a political agreement. It requires convincing governments, businesses, banks and investors that an alternative is dependable, accessible and useful on a comparable scale.
BRICS may be able to reduce reliance on the Dollar in selected areas long before it can challenge the dollar across the entire global financial system.
3. WHAT HAPPENS WHEN BRICS PAYMENT SYSTEMS REACH FULL OPERATION
The most immediate challenge to the Dollar may come not from a new banknote but from the infrastructure through which money moves across borders.
One initiative attracting attention is BRICS Pay, a proposed payment ecosystem intended to connect national payment infrastructures and facilitate cross-border transactions. Reporting by Al Jazeera in September 2026 described the project as being in pilot and phased-rollout stages, rather than operating as a fully established global replacement for existing payment networks.
If systems of this kind become widely usable, the consequences could develop across several stages.
First, direct settlement in national currencies. An importer in one BRICS country could pay an exporter in another using agreed currencies, reducing the need for an intermediate dollar conversion. Whether this saves money would depend on exchange rates, fees, liquidity and the availability of willing counterparties.
Second, faster cross-border payments. Connecting national payment systems could reduce delays and transaction costs. This would be particularly important for smaller businesses that struggle with the costs and administrative burdens of international transfers.
Third, greater choice for banks and businesses. Companies could choose among available settlement currencies and payment routes rather than relying on a single dominant channel for every transaction.
Fourth, a gradual shift in demand for Dollars. If more trade can be settled directly in national currencies, some businesses and financial institutions may need to hold fewer Dollars for transaction purposes.
However, the final outcome will depend on adoption. A payment platform cannot automatically make a currency attractive as a store of value, nor can it eliminate exchange-rate risks, capital controls or differences between national banking regulations.
The distinction matters: a successful alternative payment system could weaken the Dollar’s role as an intermediary without displacing it as the world’s leading reserve currency.
4. THE NEW DEVELOPMENT BANK: BRICS’ FINANCIAL FOUNDATION
Beyond payment systems, BRICS has an existing financial institution with a potentially important role in reducing dependence on conventional international financing channels.
The New Development Bank (NDB), established by the founding BRICS countries, finances infrastructure and sustainable development projects. Its work provides a practical foundation for financial cooperation beyond discussions about a future currency.
At the September 2026 summit, BRICS leaders encouraged the bank to expand its ability to mobilise resources, diversify funding, increase local-currency financing and support infrastructure investment in emerging economies.
This matters because a currency’s international influence is built partly through the availability of loans, bonds and other financial assets denominated in that currency.
Imagine an African country borrowing in its own currency or in the currency of a major trading partner to build a railway, electricity network or industrial park. If the project generates revenue in that same currency, the borrower may face less exchange-rate risk than it would under a dollar-denominated loan.
But local-currency lending is not automatically cheaper. Interest rates, inflation, currency convertibility and the lender’s access to funding all affect the final cost.
For BRICS, the strategic opportunity is to create a wider ecosystem in which development finance, cross-border payments and trade can reinforce one another.
The NDB could contribute to that ecosystem, but it is not itself a central bank for BRICS, and its lending activities do not mean that the group has established a common currency.
5. WHY CHINA MATTERS — AND WHY THE RENMINBI IS NOT YET A DOLLAR REPLACEMENT
China occupies a central position in the de-Dollarisation debate because of its enormous manufacturing capacity, extensive trade relationships and influence over global supply chains.
The renminbi, also called the yuan, offers countries that trade extensively with China a practical option for settling some transactions without first converting their money into Dollars.
For example, a country importing machinery, electronics or industrial equipment from China could negotiate payment in renminbi. A Chinese exporter could then use the proceeds to pay Chinese suppliers or meet other obligations in the same currency.
This creates a natural incentive for businesses with substantial China-related trade to use the renminbi.
Nevertheless, the IMF’s first-quarter 2026 figures put the renminbi at just 1.99% of allocated global foreign-exchange reserves, compared with 57.13% for the Dollar.
The difference illustrates the gap between being a major trading currency and being a leading global reserve currency.
To compete more directly with the dollar, the renminbi would need broader international confidence, greater access to liquid financial assets, and fewer practical obstacles for foreign investors seeking to move capital into and out of Chinese markets.
China’s capital controls and the management of its exchange-rate regime are important considerations for investors evaluating how freely the currency can be used internationally.
Moreover, other BRICS members have their own interests. India, for example, may support more local-currency trade without wanting the renminbi to become the dominant currency in a new system.
BRICS cooperation is therefore not synonymous with a Chinese-led monetary union.
6. CAN OIL AND OTHER COMMODITIES WEAKEN THE DOLLAR’S GRIP
Energy is one of the most important arenas in which alternative currency arrangements could affect dollar demand.
Oil and other internationally traded commodities have traditionally relied heavily on Dollar pricing and settlement. This practice creates a recurring need for Dollars among importers, exporters, financial institutions and commodity traders.
If more energy transactions between BRICS members and their trading partners were priced and settled in national currencies, some of that transactional demand could shift.
Consider an illustrative transaction involving an oil exporter and an importer. If both agree to settle payment in their respective national currencies through an arrangement that manages conversion and exchange-rate risk, the dollar may no longer be necessary as the intermediary currency.
Multiply that possibility across oil, gas, coal, agricultural products, metals and manufactured goods, and the potential for gradual change becomes clearer.
However, pricing a commodity in dollars and paying for it in another currency are two different things.
A transaction can be priced against a dollar benchmark but settled in another currency using an agreed exchange rate. Consequently, the use of non-Dollar payments does not necessarily eliminate the dollar’s influence on commodity pricing.
Furthermore, energy exporters must decide what to do with the currencies they receive. If they cannot readily spend, invest or exchange those funds, they may prefer dollars despite the availability of alternative payment arrangements.
The challenge for BRICS is therefore not merely to encourage non-Dollar payments, but to develop liquid markets and dependable ways for participants to reuse the currencies they receive.
7. WHAT WOULD HAPPEN TO THE US DOLLAR IF BRICS ACHIEVED ITS full AMBITIONS
The consequences would depend on how extensively the emerging system was adopted.
Scenario One: Gradual diversification
More BRICS trade is settled in national currencies, while the Dollar remains the principal global reserve currency. Businesses gain additional payment options, and the dollar loses some transactional demand in selected trade corridors.
Scenario Two: A multipolar financial system
Several currencies become more important for reserves, lending, investment and international payments. The dollar remains influential, but the Euro, renminbi and other currencies gain ground in particular markets.
Scenario Three: A significant decline in Dollar dominance
If alternative financial markets become sufficiently liquid and trusted, governments and investors could reduce their dollar holdings more substantially. This could increase US borrowing costs and reduce some of Washington’s financial leverage, although the scale would depend on how investors reallocate their assets.
These are analytical scenarios, not predictions or established outcomes.
The first is consistent with BRICS’ current emphasis on practical payment arrangements. The second would require wider and sustained adoption of alternative currencies and financial assets. The third would require a much deeper change in global investment behaviour than simply launching a new payment platform.
Even if BRICS achieved its ambitions, the dollar could remain the largest reserve currency for many years. Currency transitions tend to depend on confidence, liquidity, institutional quality and the availability of alternatives, not simply on the size of a political or economic bloc.
8. THE POTENTIAL COSTS FOR AMERICA
The Dollar’s international role brings substantial advantages to the United States.
Global demand for dollar assets helps sustain a large market for US government securities and supports the currency’s use in international finance. It also gives American authorities significant influence over parts of the international financial system.
If demand for dollar assets weakened materially, the United States could face several potential consequences.
Higher borrowing costs: If foreign and domestic investors demanded greater compensation to hold US government debt, Treasury yields could rise, increasing the cost of financing government deficits and potentially influencing borrowing costs across the economy.
A weaker Dollar under some conditions: A sustained reduction in demand for Dollar assets could put downward pressure on the exchange rate. A weaker dollar could make American exports more competitive, but also make imports more expensive.
Reduced financial leverage: If countries developed credible alternative payment and financing channels, the reach of some US financial restrictions could become less extensive. The effect would depend on the specific transactions, institutions and jurisdictions involved.
Changing international investment patterns: Businesses and investors might diversify their holdings among different currencies and markets, potentially reducing the relative advantage enjoyed by US financial markets.
None of these outcomes is automatic. Treasury yields, the Dollar’s exchange rate and international investment flows are influenced by many factors, including inflation, Federal Reserve policy, economic growth, fiscal conditions and global risk appetite.
There is also a countervailing consideration: a large, liquid US Treasury market remains attractive to investors seeking assets that can be traded in substantial volumes. The Federal Reserve’s 2025 assessment highlighted the depth and liquidity of US financial markets as important supports for the Dollar’s position.
The US Dollar’s greatest challenge may therefore come not from a sudden collapse, but from the gradual erosion of advantages that have made it the default choice for international transactions.
9. WHY A COMMON BRICS CURRENCY REMAINS A DIFFICULT PROPOSITION
The idea of a single BRICS currency is attractive to some supporters because it could, in principle, provide an alternative unit for trade and finance across the bloc.
But creating a common currency among sovereign states is a far more demanding undertaking than connecting their payment systems.
The participating countries have different economic structures, inflation rates, monetary policies, exchange-rate arrangements and capital controls.
They also have different political priorities and levels of economic integration.
A common currency would raise difficult questions: Who would issue it? Which institution would manage its supply? How would its value be determined? Who would provide emergency liquidity during a financial crisis? And how would the system handle disagreements between member states?
The experience of existing monetary unions demonstrates that a shared currency requires more than agreement on a banknote or digital token. It requires institutions and rules capable of managing economic tensions between participating economies.
As of the September 2026 BRICS summit, India explicitly stated that no proposal for a common BRICS currency was on the table. The group’s official declaration instead called for continued work on cross-border payment interoperability and local-currency settlements.
That makes a gradual, decentralised approach more relevant to the current debate than claims that a common BRICS currency is imminent.
10. THE HIDDEN OBSTACLE: WHAT HAPPENS WHEN COUNTRIES ACCUMULATE EACH OTHER’S CURRENCIES
One of the less-discussed problems in de-Dollarisation is the question of currency balances.
Suppose Brazil exports agricultural products to China and receives renminbi. If Brazil imports enough Chinese goods, it can use those balances to pay Chinese suppliers.
But what happens if Brazilian exporters earn substantially more renminbi than Brazilian importers need?
Brazil would need ways to invest, exchange or otherwise use the surplus. That might involve buying Chinese assets, lending to Chinese businesses or converting the proceeds into another currency.
If the alternatives are unattractive or difficult to access, the exporter may prefer dollar settlement.
This is why payment infrastructure alone cannot complete the transition.
A functioning alternative system needs deep markets for investment, transparent exchange rates, reliable settlement procedures, mechanisms for handling trade imbalances and sufficient confidence that participants can convert or spend the currencies they receive.
It also needs clear rules for dispute resolution, fraud prevention, compliance and the movement of capital across borders.
The BRICS New Delhi Declaration itself recognises that there is no single approach suitable for every member and calls for further work on secure, efficient and accessible payment mechanisms.
These practical details may determine the eventual reach of BRICS initiatives more than political declarations about ending dollar dominance.
11. WHAT DOES ALL THIS MEAN FOR AFRICA AND NIGERIA
For African economies, the implications could be considerable.
Many African businesses import machinery, pharmaceuticals, fuel, electronics and industrial inputs while earning revenue in local currencies. When their transactions depend heavily on Dollars, they can face foreign-exchange shortages, conversion costs and exposure to exchange-rate fluctuations.
Nigeria provides a particularly relevant example because its international trade, external obligations and foreign-exchange market are affected by the availability and cost of foreign currency.
If BRICS-linked payment arrangements become practical and widely accessible, Nigerian importers and exporters could potentially gain additional ways to settle eligible transactions with trading partners.
A Nigerian company importing machinery from China, for example, might be able to arrange payment in renminbi if its supplier, banks and applicable regulations support the transaction.
Similarly, exporters could benefit if they could receive, hold and use alternative currencies without facing excessive conversion costs or settlement risks.
For Nigeria, the potential benefits include:
- Lower transaction costs where direct settlement is genuinely cheaper.
- More payment options for businesses trading with BRICS economies.
- Reduced dependence on dollar liquidity for some eligible transactions.
- Greater opportunities for regional trade, industrial investment and infrastructure financing.
However, the benefits would not automatically resolve Nigeria’s foreign-exchange challenges.
The Naira would still be influenced by domestic inflation, productivity, monetary policy, investor confidence, export earnings and the balance between foreign-currency demand and supply.
Nor would conducting more trade in renminbi or rupees automatically make imported goods cheaper. If the Naira weakens against the currency used for settlement, import costs could rise just as they would under dollar settlement.
Nigeria would therefore need to evaluate alternative arrangements transaction by transaction, taking account of exchange rates, fees, liquidity, convertibility and the availability of currency for future payments.
The wider opportunity is to diversify access to finance and trade, not to exchange one form of currency dependence for another.
12. COULD BRICS RESHAPE THE INTERNATIONAL FINANCIAL ORDER WITHOUT DEFEATING THE DOLLAR
Yes. This may ultimately be the most consequential possibility.
A financial system does not need a single dramatic replacement event to change. Its structure can evolve as businesses adopt different payment channels, central banks diversify reserves, lenders offer financing in additional currencies and investors gain access to new markets.
The euro’s established international role already demonstrates that the Dollar does not operate in a world with only one relevant currency. The question is whether BRICS members can build additional alternatives that are sufficiently reliable to attract sustained use.
There are also important limits to the bloc’s collective strength.
BRICS members do not share identical strategic interests, and their economic relationships with the United States differ. Some may seek greater monetary independence while retaining extensive access to American markets and financial institutions.
Others may prioritise regional trade or the reduction of transaction costs rather than an explicit campaign against the Dollar.
The September 2026 declaration’s emphasis on national priorities and the absence of a one-size-fits-all approach reflects these differences.
Consequently, a more plural financial system could emerge without BRICS becoming a unified monetary bloc.
The Dollar might retain its leading position while other currencies gain importance in particular regions, commodities and trading relationships.
For the United States, such a development could mean less exclusive influence over international finance. For other countries, it could mean greater flexibility in choosing how to trade, borrow and invest.
For the global economy, the outcome could be a system with more options but also more complex exchange-rate relationships, settlement arrangements and regulatory requirements.
CONCLUSION: THE DOLLAR MAY LOSE GROUND WITHOUT LOSING ITS CROWN
The future of the US Dollar will not be determined by the size of BRICS alone, nor by a single summit declaration announcing a new currency.
It will depend on whether the expanded group can convert its economic weight into a dependable network of payment systems, financial markets, investment channels and local-currency trade arrangements.
The most important distinction is that reducing dependence on the Dollar is not the same as replacing the Dollar.
BRICS can make progress toward the first objective without achieving the second. If its initiatives mature, companies and governments may have more ways to conduct international business, and the Dollar could lose some of its existing transactional and financial advantages.
Yet the Dollar begins from a position of substantial strength, supported by the depth of American financial markets, the availability of Dollar assets and its established place in international banking and trade.
The IMF’s first-quarter 2026 data, showing the dollar at 57.13% of allocated official foreign-exchange reserves, demonstrate that its leading reserve role remains firmly established even as alternatives are discussed.
The most plausible long-term question is therefore not whether the dollar will suddenly vanish when BRICS comes full circle. It is whether the world will gradually move from a system overwhelmingly centred on the dollar toward one in which several currencies and payment networks coexist.
If that transition gathers momentum, the dollar may remain a central pillar of global finance—but it may no longer be the unavoidable intermediary for as many transactions as it is today.
For BRICS, success would mean building credible alternatives that work in everyday commerce. For the United States, the challenge would be to preserve confidence in its currency and institutions. For developing countries such as Nigeria, the opportunity would be to use greater financial choice to reduce costs, expand trade and support productive investment.
Ultimately, the fate of the dollar will be decided less by political slogans than by the choices of central banks, businesses, lenders and investors—and by which financial arrangements prove most useful, liquid, secure and trustworthy in the real economy.
™️©️ Samuel Abasiekong-Abasiekong, CEO/EiC @ www.efeederstation.com